Global Mobility Immigration and Tax

Global Mobility, Immigration and Tax

6 Apr 2023

Streamlined Coordinated Services – Immigration and Tax

Transitioning key talent from one country to another presents complex issues for the multinational corporation. Global mobility requires coordination of services between in-house legal, human resources, and other divisions in multiple countries. The typical approach is to hire one of the large immigration firms and the big accounting firms to handle the immigration and tax work, believing this is the best way forward. We have seen too often under this model that the services are not customized and collaborative to the multinational corporation or the employee transitioning to work in a new country.

Read more >

Not Over Taxing Gains on Qualified Small Business Stock

QSBS

30 Mar 2023

Not Over Taxing Gains on QSBS (Qualified Small Business Stock)

The exclusion from gain applicable to the sale of qualified small business stock (“QSBS”) is a key benefit in selecting C corporation status for startups and other businesses. QSBS stock allows the noncorporate taxpayer to exclude from gain the greater of $10 million or ten times the taxpayer’s basis in the stock (“QSBS Eligible Exclusion Amount”). Properly excluding this gain from tax is an important tax savings opportunity and significantly increases the noncorporate taxpayer’s return on investment.

Read more >

23 Mar 2023

Power of the CRUT and Importance of Correct Tax Reporting to Receive the Desired Benefits

Family offices and private clients (“Clients”) have complicated investment and estate planning structures that require professionals to understand how to handle the needs from legal, accounting, and tax reporting. One of the planning tools frequently implemented for these Clients is a charitable remainder unitrust (“CRUT”). The CRUT allows for the tax-free liquidation of a highly appreciated asset, the tax-free growth of the assets inside the CRUT, with the income building inside the CRUT only being taxed to the extent of distributions to the lifetime beneficiary. This is a powerful tool if the tax reporting occurs correctly. We have noticed a gap between the estate planning and the tax reporting often resulting in phantom income being taxed to the detriment of the beneficiaries.

Read more >

16 Mar 2023

Customized Mergers and Acquisitions Due Diligence Services

In the acquisition of a business, it is important the buyer has a clear understanding of the target’s financial, commercial, operational, technical, human capital, and tax condition. Too often, certain parts of the due diligence do not receive the attention required, either because the firm performing the due diligence does not have the necessary background, or there is a lack of coordination among professionals in different fields of expertise. This is a critical opportunity for the buyer to learn of issues with the target as the nonidentification of key issues will have a financial impact down the road for the buyer.
Read more >

16 Mar 2023

Tax Preparation for Clients with International Assets and Businesses 

U.S. tax reporting for U.S. persons with businesses or assets outside the U.S. is complex, legal intensive, and there are many traps for the unwary that can carry serious penalties. The tax preparer must understand the forms to prepare, understand the rules as the tax preparation software has not caught up to the complexity of the reporting, and be prepared to take legal positions to obtain the best result for the client. Too often, tax preparers do not have the necessary background to handle the tax reporting for international clients.

Read more >

25 Feb 2023

Customized Tax Preparation as Key Strategy for Tax Savings

We routinely see mistakes in the reporting on tax returns provided by the previous tax preparer and the tax planning strategy provided in a legal memorandum, thus missing the tax savings desired. This can result for many reasons such as the client did not provide the memorandum to the tax preparer, the tax preparer did not understand how to report the tax strategy, practically the tax strategy did not work, or that the tax preparer and attorney advisor did not work together collaboratively. Our approach is to not make it the responsibility of the client to ensure the tax strategy is carried out, but to have advisors with legal backgrounds at the table with the tax preparer collaborating together to ensure the desired result is carried out.

Read more >

Praestans | Customized Fund Administration

24 Feb 2023

Customized Fund Administration Services

Fund managers frequently experience a lack of coordination between their legal, accounting, and fund administration services.  Often fund managers receive a preset of services that are not customized to their fund, are faced with minimum service prices, and experience long response times from each set of professionals.  We provide cohesive services amongst professionals customized to the needs of our clients.  This provides our clients with the best services that are tailored to our clients' needs.

Read more >

Accounting, tax planning

12 Mar 2025

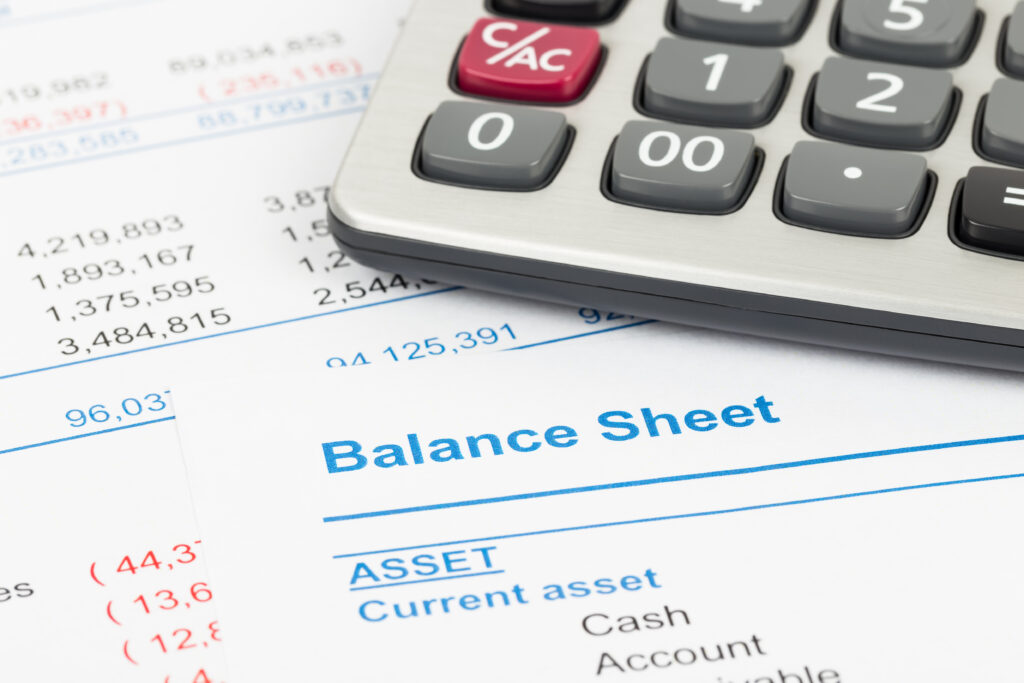
The Balance Sheet: A Key Financial Statement

Whether you are a business owner, employee, or investor, understanding how to read and understand the information on a balance sheet is an essential financial accounting skill.

Read more >

Balance sheet report with calculator; document is mock-up

Accounting, tax planning

6 Mar 2025

Typical Types of Accruals on the Balance Sheet 

The revenues that a company has not yet received payment for and expenses that companies have not yet paid are called accruals. There are four types of accruals that are typically recorded on the balance when the company follows the accrual method of accounting.

Read more >

Accounting, tax planning

13 Feb 2025

Accrual Method of Accounting

Accrual basis accounting is a method of accounting that records transactions when they occur, not when cash is received or paid out. The accrual method of accounting is used to recognize revenue and expenses in the fiscal year they are earned or incurred.

Read more >

Accounting, tax planning

6 Feb 2025

Cash Method of Accounting

Cash basis accounting is a method of accounting that records income when cash is received and expenses when they are paid. It is also known as the cash method of accounting. The cash basis of accounting is usually followed by individuals and small companies.

Read more >

Accounting, tax planning

5 Dec 2024

Follow the Cash Flows of the Acquisition to Understand the True Return to the Sellers

Cross-border acquisitions usually have additional complexities as the laws of more than one country must be planned for and coordinated.  Typical acquisition planning in one country may be different than in another country.  A structure that is common in one country may significantly change the deal for an acquiror or target in another country.

Read more >

Accounting, tax planning

24 Oct 2024

Strategic Coordination of Accounting and Tax for the Family Office and Dynasty Trust

The typical family office has a sophisticated tax structure that must blend income tax planning with estate tax planning. The structure typically involves a number of business entities that will include owners involving individuals and one or more dynasty trusts for efficient estate and gift tax planning.

Read more >

avoid double taxation, FATCA compliance for U.S. citizens, tax filing, tax for U.S. citizens and U.S. tax residents

14 Mar 2024

U.S. Taxation of U.S. Citizens and U.S. Tax Residents Residing Overseas – Foreign Bank Accounts

The government does not annually tax wealth.  However, the IRS wants to know about funds U.S. Persons have in foreign bank accounts.  There are now two different reporting requirements for foreign bank accounts, the Foreign Bank Account Report (“FBAR”) and the individual reporting requirement under the Foreign Account Tax Compliance Act (“FATCA”).

Read more >

avoid double taxation, tax filing, tax for U.S. citizens and U.S. tax residents

29 Feb 2024

U.S. Taxation of U.S. Citizens and U.S. Tax Residents Residing Overseas – Mitigation of Double Taxation

There are two methods that a U.S. Person living abroad can use to reduce their U.S. tax liability.  The two methods are the Foreign Earned Income Exclusion (“FEIE”) and the Foreign Tax Credit (“FTC”).  Even if one of these methods were to eliminate the U.S. Person’s U.S. tax liability, the U.S. Person is still required to file their U.S. tax return if their income exceeds the filing thresholds for the tax year. 

Read more >

tax filing, tax for U.S. citizens and U.S. tax residents

15 Feb 2024

U.S. Taxation of U.S. Citizens and U.S. Tax Residents Residing Overseas

U.S. citizens and U.S. tax residents (“U.S. Persons”) are taxed in the United States on their worldwide income no matter where in the world they reside. The U.S. taxes based on citizenship, which is different than almost all other countries in the world that tax based on residence. This often catches U.S. Persons who have never lived in the U.S. or have lived abroad for a number years by surprise. Any U.S. Person living abroad with income for tax year 2023 above the following thresholds must file a U.S. tax return:

Read more >

tax filing

1 Feb 2024

Tax Filings for the International Executive

Recently we were transitioning to take over the tax filing for an executive who was a U.S. tax resident because he had a green card but resided outside the U.S.  This executive has considerable income and the country that he resided in also taxed at higher rates than the U.S. federal income tax rates. Our review of the executive’s tax return not only found there were informational reporting errors, but that the income of the executive had been over reported by more than $160,000

Read more >

PFIC, PFIC Testing

18 May 2023

PFIC Testing for Foreign Portfolio Companies

Funds with U.S. investors, U.S. family offices, and individual U.S. investors (collectively, “U.S. Investors”) must be cognizant of whether their foreign investment in private companies is an investment in a passive foreign investment company (“PFIC”). Typically, a foreign portfolio company would be classified as a corporation for U.S. income tax purposes unless an election was made to have it taxed otherwise. The issue with PFICs is that unless certain elections are made, distributions from a PFIC may be subject to an excess distribution regime resulting in a punitive tax and interest charge. In certain bad circumstances, the punitive tax and interest charge can be the amount of the distribution.

Read more >

Get regular Key Service Insights newsletters, as well as other important updates, sent to your inbox.